Fed Stablecoin Proposals: Full Reserve Backing and a November 30 Deadline
The Federal Reserve Board proposed two rules on 24 September 2026 for the payment stablecoin issuers it supervises: full backing with permissible reserve assets, standardized capital and risk management standards, custody rules, and a tailored application route for insured state member banks. Comments on both close on 30 November 2026, and Governor Michael S. Barr wants the final rule to settle interest rate, currency and redemption questions.
The Federal Reserve Board asked for public comment on 24 September 2026 on two proposals that would set the rules for the payment stablecoin issuers it supervises. Comments on both close on 30 November 2026.
Both notices of proposed rulemaking appeared in the Federal Register on 29 September 2026. The first covers reserves, capital, risk management and custody. The second sets out how an insured state member bank applies to the Board for approval of a subsidiary that would issue payment stablecoins. Neither is final, and the statute behind them has an expected effective date of 18 January 2027.
What the Board proposed on September 24
The Board released the two proposals at 2:30 p.m. EDT under the Guiding and Establishing National Innovation for U.S. Stablecoins Act, which the documents call the GENIUS Act.
The first document runs to 104 pages. Its docket number is R-1899 and its citation is 91 FR 61580, and it is titled Implementing the Federal Reserve Board's Responsibilities Under the GENIUS Act. It proposes regulations for Board-supervised permitted payment stablecoin issuers, called PPSIs in the text, along with certain other entities subject to the Board's jurisdiction. The Federal Register entry lists amendments across existing rules on bank activities, capital, holding companies and procedure.
The second document runs to 16 pages, carries docket number R-1900 and citation 91 FR 61346, and proposes procedures for an insured state member bank that seeks Board approval for a subsidiary to issue payment stablecoins.
What the first proposal would require
According to the Board's announcement, Board-supervised issuers would have to back their stablecoins fully with permissible reserve assets, described as short-term Treasury bills and certain other high-quality, liquid assets. The proposal would also set standardized capital requirements aimed at credit and operational risks in stablecoin activity, together with risk management standards.
Two further pieces sit with those requirements. The proposal would add rules for Board-supervised firms that safekeep the assets backing payment stablecoins, and it would clarify whether stablecoin and related activities are permissible for Board-supervised banks.
It also implements the statutory prohibition on tying in section 4(a)(8) of the GENIUS Act. That provision reaches further than the rest. The Federal Register notice describes the tying prohibition as applicable generally to all permitted payment stablecoin issuers, not only the ones the Board supervises.
What the second proposal would require
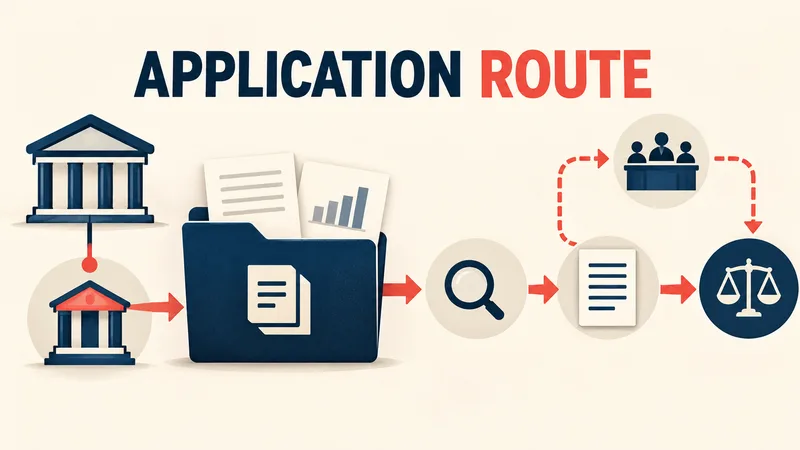
The application proposal deals with process rather than prudential standards. A bank applying to issue payment stablecoins through a subsidiary would submit a business plan and financial information, among other documents, under the Board's description of the proposal.
The same notice would set out how appeals, hearings and final determinations on those applications work.
Which firms fall under each proposal
The Board's materials describe both proposals as covering Board-supervised firms and other entities within its jurisdiction. State member banks and their subsidiaries are the clearest example of the first group.
The tying provision is the exception, because it applies to all permitted issuers. For an issuer supervised by another regulator, that single provision is the part of these two documents that would still apply directly.
The Board is not the only agency implementing the statute. The Treasury Department issued its own notice of proposed rulemaking on section 3 of the GENIUS Act on 17 August 2026, covering what it means to issue, offer or sell a payment stablecoin in the United States.
The comment deadline and the start date
Comments on both Fed proposals must be received by 30 November 2026, the date given in the Federal Register notices. The Board's announcement put it another way, saying the comment period closes 60 days after publication in the Federal Register, and the notices were published on 29 September 2026.
The statute carries its own dates. Treasury says the expected effective date of the GENIUS Act is 18 January 2027, and that from then a person generally may not issue a payment stablecoin in the United States without an appropriate federal or state license. From 18 July 2028, Treasury adds, digital asset service providers generally may not offer or sell payment stablecoins to people in the United States unless the stablecoins are issued by a licensed issuer.
Where Governor Barr wants changes
Governor Michael S. Barr supported the proposals in a statement published with the release, and used it to name the questions he wants answered.
He said he was encouraged by limits on reserve assets and by transparent, standardized capital requirements, and that public input would be useful on both, particularly on whether the rule adequately addresses interest rate and foreign currency risks. He also said universal redemption rights should be clear in the final rule, so the public can have confidence in access to their funds.
Barr returned to a concern he had raised about the Board's July 2026 proposal on bank anti-money laundering programs. In any final rulemaking for the stablecoin proposal, he wrote, he wants the Board to address a standard on anti-money laundering deficiencies. That standard would prevent the Board from taking supervisory or enforcement action unless the deficiency is significant or systemic. He described the standard's effects as potentially unknown.
He added that further work will undoubtedly be required if stablecoins are to be reliable payment instruments.
Unresolved points before a final rule
Neither document is a rule. Both are proposals, the comment window is open, and the Board can change the reserve asset list, the capital calibration, the treatment of interest rate and foreign currency risk, and the redemption provisions before anything is final.
The release does not say how many firms either proposal would cover, and it gives no estimate of compliance costs. The Board's release also gives no date for final action.
Sources & further reading
- Federal Reserve Board requests public comment on two proposals related to establishing a regulatory framework for Board-supervised payment stablecoin issuers under the GENIUS ActBoard of Governors of the Federal Reserve System · accessed Oct 12, 2026
- Statement on Proposed Regulatory Framework for Stablecoins by Governor Michael S. BarrBoard of Governors of the Federal Reserve System · accessed Oct 12, 2026
- Implementing the Federal Reserve Board's Responsibilities Under the GENIUS Act (proposed rule record)Federal Register, Office of the Federal Register · accessed Oct 12, 2026
- Application Procedures for Board-Supervised Insured Depository Institutions Seeking Approval for a Subsidiary To Issue Payment Stablecoins (proposed rule record)Federal Register, Office of the Federal Register · accessed Oct 12, 2026
- Treasury Seeks Public Comment on GENIUS Act Proposed RulemakingU.S. Department of the Treasury · accessed Oct 12, 2026